News
Industrial Relations (Provisions in Respect of Pension Entitlements of Retired Workers) Bill 2021
The Irish Senior Citizens Parliament (ISCP) along with its member organisations is presenting an update and information session in the AV Room next week, the 4th November 2025 to all TDs on this important Bill to give a voice to retired workers regarding their pension income and equality.
The bill is currently at 3rd Stage before the Dáil with the Joint Committee of Department of Trade, Tourism and Enterprise.
Please contact your local representative advising that you are a member of ISCP, requesting that they attend and look at how they can support the Bill’s progress. Ask them to respond to you with an update.
ISCP invited to Oireachtas Joint Committee on AI and Older People
Our CEO Pat Mellon and MDO Sharon Casey represented ISCP on Tuesday 30th September 2025
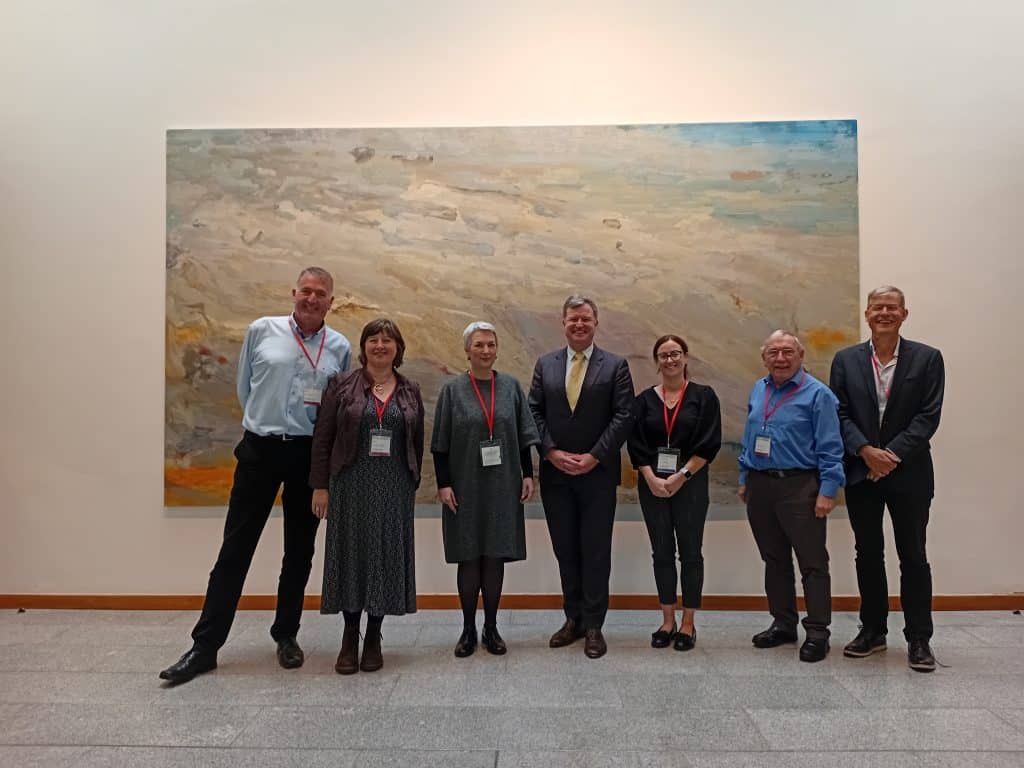
ISCP was one of three organisations invited before Oireachtas Joint Committee on Artificial Intelligence and Older People. Pictured above from left to right are Pat Mellon – CEO ISCP; Sharon Casey – Membership Development Officer ISCP; Camille Loftus – Head of Advocacy & Public affairs Age Action; Deputy Malcolm Byrne – Cathaoirleach of Joint Committee on Artificial Intelligence; Dr. Aileen O’Reilly – Head of Research, Evaluation & Policy Alone; Niall Carroll – Volunteer Age Action, Seán Moynihan – CEO Alone
Watch the proceedings at: https://www.oireachtas.ie/en/oireachtas-tv/video-archive/committees/10595
Transcript of debate available here: https://www.oireachtas.ie/en/debates/debate/joint_committee_on_artificial_intelligence/2025-09-30/2/
Health Insurance – An ISCP Member’s story
If this keeps going, we’ll need a mortgage to pay our bill’ quote from Mick Casey, Treasurer of ISCP
Article by Sarah O’Mahony in Irish Independent Fri 26 Sep 2025 on three generations on the soaring cost of health insurance. For Full Article please see Irish Independent. Photo curtesy of Irish Independent.
“A retired couple have told how they are struggling to afford the cost of their health insurance cover, which is now almost €6,000 a year.
Health insurance premiums across the board are rising.
Last month, VHI became the third health insurer to announce a hike in premiums in the space of a few weeks.
The state-owned insurer will increase the cost of 50 of its plans by 3pc from the start of next month.
It followed Laya Healthcare’s announcement last month that it would increase the cost of a range of its plans by an average of 4.5pc from next month, although there are also some reductions.
Irish Life Health also said last month it would raise the cost of 99 of its plans by an average of 3pc from next month, adding up to €185 a year to a family’s cost of cover.
The Irish Independent spoke to three generations about their private health cover and whether they feel they are getting value for money.
‘An old-age pensioner shouldn’t be out of pocket’
Michael Casey (82) and his wife Geraldine (82) are currently paying €5,849 a year on their VHI premium.
The retired couple from Mullingar, Co Westmeath, are on the ProvidentCare Plus plan.
In March 2023, Mr Casey, who was a telecommunications employee with the ESB, had his health insurance plan with the semi-state company transfer to the equivalent VHI plan.
Currently, his premium is reduced by a 10.5pc subsidy from an ESB fund as part of his pension plan. The subsidy, which began at 100pc, has decreased incrementally over the past three years.
The drop in that subsidy has led to an increase in Mr Casey’s plan.
Additionally, the pensioner claims there has been significant inflation of VHI’s non-subsidised premium.
“Under my previous plan, I would have spent roughly €5,200 a year,” he said. “Since March 2023, that would mean a rise of €1,335 on the non-subsidised premium figure. If this keeps going, we would need a mortgage to pay our health insurance.”
A spokesperson for VHI said the increases in the couple’s plan are mainly attributed to the reduced ESB subsidy rather than a price increase from the provider itself. “The fact is that his ex-employer was paying and funding his scheme for the first two years effectively, on a reduced level as it went on, and now he is paying the full price,” they said.
‘I always say to the GP to put us on the public system, and we’ll go the private route'”